
Executive Development Programme in Probability Fundamentals for Financial Modeling
Master probability fundamentals to enhance financial modeling accuracy, enabling robust risk assessment and data-driven strategic decision-making for executives.
Executive Development Programme in Probability Fundamentals for Financial Modeling
Programme Summary
This intensive executive programme delivers a rigorous foundation in probability theory, explicitly tailored for senior financial analysts, quantitative researchers, and risk managers seeking to enhance their modelling capabilities. Participants engage directly with core stochastic concepts, including conditional probability, Bayes’ theorem, and random variable distributions, within the context of real-world financial markets. The curriculum bridges the gap between abstract mathematical theory and practical application, ensuring that professionals from diverse non-mathematical backgrounds can confidently interpret complex statistical outputs. By focusing on the probabilistic nature of asset prices and market volatility, the course equips leaders with the analytical framework necessary to navigate uncertainty in high-stakes decision-making environments.
Learners acquire the technical proficiency to construct robust financial models that accurately reflect market dynamics and risk exposures. The training emphasises the derivation of probability density functions and the application of Monte Carlo simulations for pricing derivatives and assessing portfolio risk. Participants master the art of distinguishing between aleatory and epistemic uncertainty, allowing for more precise calibration of stress-testing scenarios. This deepened understanding enables executives to validate model assumptions critically, thereby reducing the likelihood of significant pricing errors or capital misallocation in volatile trading conditions.
Mastery of probability fundamentals significantly elevates a professional’s credibility and strategic influence within investment banks and asset management firms. Graduates demonstrate the ability to communicate complex risk metrics to stakeholders with clarity and precision, fostering greater confidence in quantitative strategies. This expertise positions individuals for advancement into senior quantitative roles, chief risk officer positions, or specialised heads of model validation
Learning Outcomes
Mastering probability is the bedrock of sophisticated financial modeling, yet many practitioners struggle to bridge the gap between theoretical statistics and practical application. This Executive Development Programme addresses that critical skill gaps by immersing senior professionals in the probabilistic frameworks that underpin modern quantitative finance. Participants will move beyond basic descriptive statistics to explore stochastic processes, conditional expectations, and Monte Carlo simulations with rigorous mathematical precision.
The curriculum is meticulously designed to reflect real-world market complexities. Learners will dissect the mechanics of Brownian motion, understand the nuances of risk-neutral valuation, and apply Bayesian inference to dynamic portfolio management. Through intensive case studies drawn from leading investment banks and asset management firms, attendees will construct robust models for pricing exotic derivatives, assessing credit risk, and optimizing capital allocation under uncertainty. These exercises are not merely academic; they replicate the high-stakes decision-making environments participants encounter daily.
Graduates emerge with the confidence to validate existing models, identify structural weaknesses, and develop novel strategies for risk mitigation. They learn to communicate complex probabilistic insights to non-technical stakeholders, ensuring that quantitative rigor translates into strategic advantage. This capability is indispensable for roles such as Quantitative Analyst, Chief Risk Officer, and Head of Financial Engineering.
Career prospects for programme alumni are expansive. Financial institutions increasingly seek leaders who can navigate volatile markets with analytical certainty. By mastering these fundamentals, executives position themselves for senior leadership roles within global banks, hedge funds, and fintech enterprises. The programme offers a decisive competitive edge, equipping professionals
Programme Features
Industry-Aligned Curriculum
Developed with industry leaders for job-ready skills
Globally Recognised Certificate
Recognised by employers across 180+ countries
Flexible Online Learning
Study at your own pace with lifetime access
Instant Access
Start learning immediately, no application process
Constantly Updated Content
Latest industry trends and best practices
Career Advancement
87% report measurable career progression within 6 months
Course Modules
- Probability Axioms and Sample Spaces: Establishes the mathematical foundation including Kolmogorov axioms and event definitions.: Conditional Probability and Independence: Analyzes how prior knowledge affects likelihood and defines statistical independence.
- Discrete Random Variables: Examines distributions such as Binomial and Poisson relevant to countable financial outcomes.: Continuous Random Variables: Covers essential distributions like Normal and Log-Normal used for asset price modeling.
- Expectation and Variance: Calculates central moments to quantify expected returns and risk volatility.: Joint Distributions and Covariance: Explores relationships between multiple variables to model portfolio diversification effects.
What's Included in This Programme
Here is what you get when you enrol with LSBR London
Programme Facts
Audience: Senior finance professionals and quantitative analysts seeking rigorous statistical grounding.
Prerequisites: Undergraduate mathematics proficiency and basic financial market knowledge.
Outcomes: Master stochastic processes for robust financial model construction and risk assessment.
Ready to advance your career?
Join thousands of professionals who have transformed their careers with LSBR London. Enrol today and start learning immediately.
Why Study This Programme
The ‘Executive Development Programme in Probability Fundamentals for Financial Modeling’ offers a critical competitive advantage for finance professionals seeking to refine their analytical rigour. This course bridges the gap between theoretical mathematics and practical application, ensuring participants can navigate complex market dynamics with confidence.
Enhanced Decision-Making Precision: Participants master stochastic calculus and Monte Carlo simulations, enabling them to construct more accurate risk assessment models. This proficiency directly translates into superior capital allocation strategies, reducing exposure to unforeseen market volatility and improving portfolio resilience.
Advanced Derivatives Pricing Capabilities: The curriculum provides deep insights into option pricing mechanisms, including Black-Scholes-Merton adjustments. Professionals gain the ability to price exotic derivatives accurately, a skill highly valued by investment banks and hedge funds seeking to optimise trading book performance and manage counterparty risk effectively.
Robust Stress Testing Frameworks: Learners develop sophisticated scenario analysis techniques, allowing them to evaluate extreme market conditions. This capability is essential for regulatory compliance under Basel III standards, ensuring that financial institutions maintain adequate capital buffers while demonstrating robust governance to stakeholders.
Strategic Career Advancement: Completion of this programme signals a high level of quantitative competence to employers. It distinguishes candidates for senior roles in quantitative analysis, risk management, and asset management, where data-driven insights are paramount. Graduates often experience accelerated promotion trajectories due to their enhanced ability to interpret probabilistic outcomes and communicate complex risks to non-technical executives. This targeted skill acquisition ensures long-term relevance
"This programme gave me the confidence and credentials to secure a senior role. Highly recommend LSBR London."
— Sarah M., United Kingdom
Course Brochure
Download our comprehensive course brochure with all details
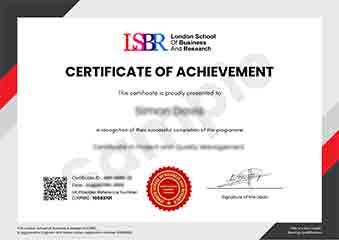
Sample Certificate
Preview the certificate you'll receive upon successful completion of this program.
Get Course Info
Receive the full course guide, pricing details, and enrolment instructions directly in your inbox.
Check your inbox!
Course details have been sent to your email.
Get Your Employer to Sponsor This Programme
Many employers offer professional development budgets. We make it easy for your company to invest in your growth with corporate invoicing and bulk enrolment options.
Email Template for Your Manager
Dear [Manager's Name],
I would like to request sponsorship for the Executive Development Programme in Probability Fundamentals for Financial Modeling programme offered by LSBR London - Executive Education.
The programme costs $199 (one-time) and can be completed in 3-4 weeks alongside my regular duties.
Key benefits to our team:
- Immediately applicable skills
- Globally recognised certificate
- Corporate invoice available
Best regards,
[Your Name]
What Our Students Say
Hear from our students about their experience with the Executive Development Programme in Probability Fundamentals for Financial Modeling at LSBR London - Executive Education.
Oliver Davies
United Kingdom"The course material provided a rigorous yet accessible foundation in probability theory, directly bridging the gap between abstract concepts and real-world financial applications. I now feel confident in applying stochastic models to risk assessment and pricing scenarios, which has significantly enhanced my analytical toolkit for professional decision-making."
Fatimah Ibrahim
Malaysia"Mastering the probabilistic foundations of financial modeling has significantly sharpened my ability to construct robust risk assessment frameworks for complex derivatives. This practical expertise directly accelerated my transition into a senior quantitative analyst role, where I now lead the development of more accurate pricing models."
Wei Ming Tan
Singapore"The logical progression of the modules made complex probability concepts accessible and directly applicable to my daily financial modeling tasks. This structured approach significantly enhanced my ability to quantify risk with greater precision, providing an immediate boost to my professional confidence."
Your Certification Journey
Four simple steps from enrolment to your globally recognised certificate
Enrol Online
Complete your enrolment in under 2 minutes with secure checkout
Start Learning
Get instant access to all course materials and start at your own pace
Complete Modules
Work through the curriculum with expert support available throughout
Get Certified
Receive your LSBR London certificate recognised across 180+ countries
LSBR London by the Numbers
Join a global community of professionals advancing their careers
Students Enrolled
Countries Represented
Average Rating
Career Progression